Elville and Associates

Blog / Spotlight

Blog

All Spotlight Blog Videos & Webinar Recordings News Estate Planning estate financial power of attorney financial planning Probate Wills and Trusts beneficiary elder law estate plan attorney digital assets elville and associates financial planners guardianship guardianships Healthcare income tax inheritance power of attorney public benefits special needs planning trust will Access to Music advance medical directive advance medical directives Aid & Attendance Attorney-Client Relationship Beneficiaries Beneficiary Designations Business Planning capital gain Charles A. Borek Client Care Program Consultations Coronavirus (COVID-19) Creative Arts Education elder care Elville Center Elville Center for the Creative Arts Estate and Trust Administration estate litigation estate planning attorney Estate Taxes family Governor Hogan guardian guardianship of the person in terrorem clause incapacity planning including the location Justin M. Ginsburg letter of wishes Music National Health Crisis National Healthcare Decisions Day nationwide health crisis non-probate assets planning attorney powers of attorney probate assets Proper Beneficiary Designations Remote Notarization of Documents Retirement Accounts Retirement Plan Assets revision revocable living trust Schools Secure Act social security administration social security disability insurance social security, Special Needs special needs trust spendthrift clause spendthrift clauses spendthrift trust ssi Super Lawyers supplemental security income survivorship tax Tax Planning testator the business monthly The Elville Center for the Creative Arts The Secure Act Trust Protector Trust Protectors trusts updating of your will Verena veterans administration Waypoint Trust Group
life insurance and estate planning

How Life Insurance Is Involved in Estate Planning

At first glance, life insurance may not seem related to the distribution of money and property in your estate plan. However, it can be an integral and important part of a well-drafted estate plan. In addition to providing a sizable sum of money to your heirs, a life insurance policy offers other benefits. These include the following: provides immediate cash upon death that can pay debts, final income taxes of the insured, and funeral expenses can pay estate taxes and avoid the forced sale of assets proceeds of a life insurance policy will pass to the named beneficiary free of income tax proceeds can be transferred to a trust as part of a will that the insured had created for the benefit of minor children, special needs, or aging relatives proceeds can be payable to someone other than the insured's estate when owned by an irrevocable insurance trust (For example, the funds can pay marital settlement obligations for spousal or child support.) a policy can fund a buyout of the insured's interest in a closely held business proceeds transfer to your loved ones outside probate, the court process of validating one's will Life insurance ensures your loved ones have cash funds immediately available. Often, the passing of a family member comes with unexpected expenses. Many Americans have investments such as real estate or retirement accounts like 401(k)s. However, these types of assets are not liquid. Having liquid assets available when a family member dies can prove crucial. It allows for immediate access to cash funds for such expenses as funeral costs or outstanding debts. Without liquid assets, loved ones may face financial strain. They may have to wait for lengthy probate processes before they can access certain other assets. This can cause unnecessary stress during an already difficult time. Life insurance proceeds protect families from having to force the sale of homes and other investments at unfavorable tax rates. For example, you may have a home or a car that you have not paid off. If you passed away, this could leave your family with short-term liabilities requiring cash to make ongoing payments. Understanding Estate Planning Strategies With a Life Insurance Policy One of the more popular estate planning strategies that fit many situations is an irrevocable life insurance trust (ILIT). An ILIT can hold a life insurance policy outside the insured person's estate. This ensures that the proceeds are not subject to estate taxes. So, the policy helps provide financial security for your loved ones without being part of the taxable estate. You cannot change or revoke an ILIT once you have set it up. A beneficiary or third party also can’t rescind the trust, modify, or amend it. However, heirs gain several financial and legal advantages with an ILIT. These include asset protection, favorable tax treatment, and assurance that they will be using the proceeds in a manner concurrent with the benefactor's wishes. Typically, life insurance policies are the chief assets held in an ILIT. Before purchasing a life insurance policy, particularly if you are seeking to create an ILIT, it is always a good idea to speak with an estate planning and elder law attorney at Elville and Associates. They will be able to walk you through the potential income and estate tax consequences. If you have an estate large enough, it may be subject to federal and state estate taxes depending on the applicable laws in place at the time of your passing. Ensure that your ILIT is in place before binding a life insurance policy to it. Remember that states have different laws regarding an ILIT; to avoid problems, your ILIT must follow your state's rules. Using a Gifting Strategy for Your Life Insurance Plan You may be able to gift an existing life insurance policy to your ILIT. Unfortunately, if you were to die within three years of making the gift, the policy amount may be included in the total value of your estate for tax purposes. This is because of a rule known as a "lookback period." Federal estate and gift tax exemption amounts also frequently change. So, it’s prudent to fund your ILIT by purchasing a new policy instead. Doing so will avoid the possibility of a lookback period. When using an ILIT, consider your situation before purchasing your life insurance policy and designating beneficiaries, such as whether you are married or single. Choosing between variations of permanent life insurance, such as whole standard life, universal life, and variable life insurance, can be confusing. An estate planning attorney can help guide you in these and numerous other financial affairs. If you own a business, you may have one adult child who wants to take over the business. Your other children might not be interested or involved in the enterprise. Life insurance proceeds can provide the cash to buy out the other siblings’ interests while leaving the business intact. Blended families can also benefit from life insurance payouts, too. For example, they can ensure that all children receive an inheritance, not just the children of the last surviving spouse. How to Ensure Your Estate Plan Includes Life Insurance Life insurance should be a part of your family estate plan. It can increase the wealth your heirs inherit. It also can provide a ready source of cash for immediate financial obligations after your death. Which form of life insurance best suits your needs will depend on your age and situation. Speak with an estate planning and elder law attorney at Elville and Associates about how you can effectively use a life insurance policy to transfer wealth to your loved ones. The attorneys at Elville and Associates will also offer proper guidance on the types of estate planning documents that will best serve your needs. #elvilleeducation
Elville and Associates Montgomery County Rockville

Elville and Associates, P.C. Opens New Montgomery County Office in Rockville

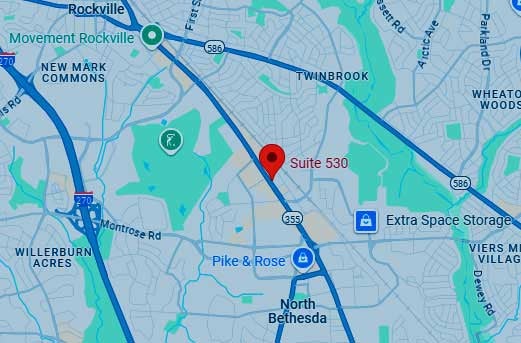
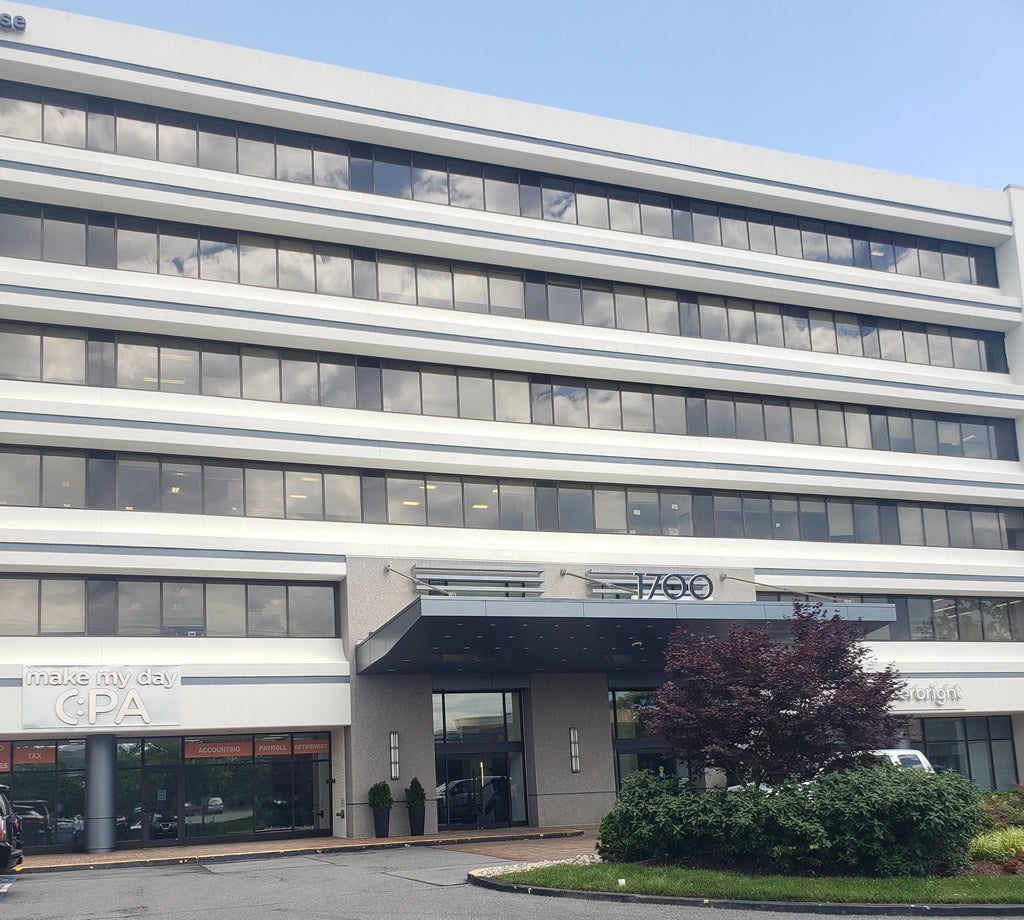
Authored by: Stephen Elville – Managing Principal and Lead Attorney – Elville and Associates, P.C. After nearly 25 years of serving residents of Montgomery County at its former Rockville and Pike and Rose locations, I’m proud to announce the opening of Elville and Associates’ new permanent Montgomery County office at 1700 Rockville Pike, Suite 530, Rockville - serving Rockville, Bethesda, Potomac, Gaithersburg, and all of Montgomery County. Montgomery County is a dynamic setting for business and government, and a diverse population with continuous and growing needs for comprehensive and contemporary estate and other related planning. Montgomery County remains largely underserved in Elder Law, now a burgeoning area of law affecting nearly all individuals and families. Elville and Associates is both proud and privileged to serve this great community and County, and to be a Member of the Bar Association of Montgomery County. If you are a community leader, nonprofit organizer, financial advisor, CPA, insurance professional, Aging LifeCare Manager, firefighter or police officer, or other collaborative professional; or, if you know someone who is in need of client care-focused, education-based estate planning, elder law planning, special needs planning, or business related planning, we invite you to contact us. We look forward to meeting you as Elville and Associates continues to serve those who make Montgomery County great. You can reach me, Stephen R. Elville, J.D., LL.M., at 443-393-7696 x108, or at steve@elvilleassociates.com. You can also reach Lillian Hummel, our Principal Attorney at the new Montgomery County office, at 240-583-7990 x201, or at Lilly@elvilleassociates.com. Or, send us a general message here. Elville and Associates, P.C. - Planning for Life, Planning for Legacies. What’s your Plan? What’s your Legacy?

CTA AF picture

The Corporate Transparency Act – It’s No Joke!

Authored by: Stephen R. Elville, J.D., LL.M. – Managing Principal and Lead Attorney Summertime fun and visions of running through daisies in slow motion – NOT! It’s another perfect June day as I write this brief blog. Many of us who love summer take to the warm air like fish to water and count each day as a bit of nirvana. But not so fast! Having presented on the Corporate Transparency Act twice in the past week and a half, my brain is on overload trying to figure out how in the world attorneys, CPAs, financial advisors, CFOs, and other professionals will be able to disseminate the nature, origin, purpose, critical definitions, requirements, and who is to report and who is exempt, both now and by the end of 2024 to save clients, business owners, family, friends, and those in spheres of influence, from the embarrassment and penalties for non-compliance with the CTA. If you are like me, having to discuss and deal with the Corporate Transparency Act is akin to having to go to the dentist on a rainy day, something unpleasant mixed with a healthy amount of uncertainty. Well, we may as well reach for some form of mental analgesic, or laughing gas, your choice, and face the music. If you or anyone you know has formed an LLC or other entity that is required to report under the Corporate Transparency Act, compliance is required within 90 days of that formation in 2024. For those persons required to report for entities formed prior to 2024, reporting must occur prior to December 31, 2024. And lastly, for those required to report for entities formed after January 1, 2025, reporting must occur within 30 days. Penalties of up to $500 per day, unlimited, for noncompliance apply, and criminal penalties of up to $10,000 apply. The Corporate Transparency Act is no joke, and as we are now at mid-year 2024 it’s essential that the requirements of this new law designed to combat money laundering, terrorism, and fraud, be disseminated as widely as possible. Whether you are planting daisies this summer or running through fields of them, be sure not to trip up by failing to understand the reporting requirements of the CTA because doing so could hurt. If you would like to know more about the Corporate Transparency Act, please reply by clicking this link contact us, and we will be happy to send you a link to my recent webinar about this important issue.

Contact Us

Fill out this form below and we'll contact you shortly
*Required Fields